
Tax Strategies Guide for Real Estate Investors
Capital gains, depreciation, 1031 exchanges, opportunity zones, cost segregation, and more — a comprehensive guide to tax considerations for real estate investors.

Key Takeaway
The difference between a well-structured and a poorly structured real estate transaction can amount to tens or hundreds of thousands of dollars in tax liability. Understanding capital gains taxation, depreciation, deferral mechanisms, and rental income sheltering strategies is generally considered important for real estate investors.
This guide is for educational purposes only. It does not constitute tax, legal, or investment advice. Tax laws are complex and subject to change. Consult a qualified tax professional before making any tax-related decisions.
Why Tax Awareness Matters for Real Estate Investors
Real estate is one of the most tax-advantaged asset classes available to individual investors. The Internal Revenue Code contains dozens of provisions that specifically benefit property owners, from annual deductions that reduce taxable rental income to mechanisms that defer or eliminate capital gains entirely. These provisions are generally understood to exist because Congress has long used the tax code to incentivize real estate investment, housing development, and property improvement.
For investors holding rental properties, commercial buildings, or other real estate assets, understanding these tax provisions is generally considered important. The difference between a well-structured and a poorly structured transaction can amount to tens or hundreds of thousands of dollars in tax liability. Four broad categories of tax strategy are relevant to most real estate investors: capital gains taxation, depreciation and cost recovery, deferral and exclusion mechanisms, and rental income sheltering.
This guide provides an educational overview of each category. It covers the major provisions, explains how they work, and identifies which strategies may be worth exploring based on an investor's specific situation. The content is informational only and does not constitute tax, legal, or investment advice. Tax rules change frequently, and individual circumstances vary. Investors should consult a qualified tax professional, such as a CPA or tax attorney with real estate experience, before making decisions based on any of the concepts discussed here.
Understanding Capital Gains Tax on Real Estate
Capital gains tax is often the single largest tax liability a real estate investor faces when selling a property. The federal tax treatment depends on how long the property was held and the investor's overall taxable income.
Short-Term vs. Long-Term Capital Gains
Properties held for one year or less generate short-term capital gains, which are taxed at ordinary federal income tax rates ranging from 10% to 37%. Properties held for more than one year may qualify for long-term capital gains treatment, which generally carries preferential rates of 0%, 15%, or 20%.
The holding period may make a meaningful difference. In a hypothetical example, an investor in the 37% ordinary income bracket who sells a property held for 11 months could pay nearly double the federal tax rate compared to selling that same property one month later. Actual rates depend on individual circumstances.
Federal Long-Term Capital Gains Rates
For the 2025 tax year, the long-term capital gains brackets for single filers are 0% on taxable income up to $48,350, 15% from $48,351 to $533,400, and 20% above $533,400. For married couples filing jointly, the thresholds are $96,700, $600,050, and above $600,050, respectively. These brackets are indexed for inflation and adjust slightly each year. The 2026 thresholds are modestly higher: $49,450 (single) and $98,900 (joint) for the 0% bracket, with the 20% rate applying above $545,500 (single) and $613,700 (joint).
The Net Investment Income Tax
High-income investors face an additional 3.8% Net Investment Income Tax (NIIT) under IRC Section 1411. This surtax applies to net investment income, including capital gains from real estate sales, when modified adjusted gross income exceeds $200,000 for single filers or $250,000 for married couples filing jointly. These thresholds are not indexed for inflation, which means more taxpayers become subject to the NIIT over time.
For an investor in the 20% long-term capital gains bracket who also owes the NIIT, the combined federal rate on real estate gains may reach 23.8%.
State Capital Gains Taxes
State taxes add another layer. Nine states impose no tax on capital gains: Alaska, Florida, Nevada, New Hampshire, South Dakota, Tennessee, Texas, Wyoming, and Missouri (which exempts capital gains despite having an income tax). On the other end, California taxes capital gains at rates up to 12.3%, New York up to 10.9%, and New Jersey up to 10.75%. Washington imposes a 9.9% capital gains tax on gains exceeding $1 million, though real estate is currently exempt from that tax.
How Capital Gains Are Calculated
The taxable gain on a property sale equals the sale price minus the adjusted cost basis, minus selling expenses. The adjusted cost basis starts with the original purchase price and adds closing costs and capital improvements (a new roof, for example), then subtracts any depreciation claimed or allowable during the holding period. Selling expenses include real estate commissions, transfer taxes, and legal fees.
Investors who want to estimate their potential liability can use our 1031 exchange tax calculator.
Depreciation: The “Phantom” Deduction
Depreciation is one of the most commonly used annual tax benefits available to rental property owners. It generally allows investors to deduct a portion of a building's cost each year, potentially reducing taxable rental income even when the property is generating positive cash flow. Because depreciation does not require an actual cash outlay, it is sometimes called a “phantom” deduction.
How Real Estate Depreciation Works
Under IRC Section 168, property owners may recover the cost of a building (but not the land) over a set period using the Modified Accelerated Cost Recovery System (MACRS). Residential rental properties are depreciated over 27.5 years using the straight-line method. Commercial and nonresidential properties use a 39-year schedule.
In a hypothetical example, an investor who purchases a residential rental property and allocates $550,000 to the building (excluding land) may deduct approximately $20,000 per year in depreciation ($550,000 divided by 27.5 years). If that property generates $50,000 in rental income and $15,000 in operating expenses, depreciation may reduce taxable income from $35,000 to $15,000. In some cases, depreciation and other deductions may create a paper loss for tax purposes, even while the property produces positive cash flow. Actual results vary based on individual circumstances.
Depreciation Recapture
Depreciation reduces taxable income during the holding period, but a portion of that benefit is generally recaptured when the property is sold. Under IRC Section 1250, the cumulative depreciation claimed (or allowable) is generally subject to recapture at a maximum federal rate of 25%. This recapture tax is separate from and in addition to the capital gains tax on the property's appreciation. For more on this topic, see our guide to depreciation recapture tax on real estate.
In a hypothetical scenario, an investor who claimed $200,000 in depreciation over a 10-year holding period could potentially owe up to $50,000 in recapture tax (25% of $200,000) at the time of sale, regardless of whether the property actually declined in value. This recapture obligation is an important consideration when evaluating the net benefit of depreciation deductions. Actual tax liability depends on individual circumstances.
Bonus Depreciation
Standard depreciation spreads deductions over 27.5 or 39 years, but bonus depreciation under IRC Section 168(k) may allow a much larger first-year deduction on qualifying assets. Bonus depreciation applies to personal property and land improvements associated with a building, such as appliances, carpeting, parking lots, fences, and landscaping. It generally does not apply to the building structure itself.
Following the passage of the One Big Beautiful Bill Act (OBBBA) in 2025, property placed in service after January 19, 2025, may qualify for 100% bonus depreciation. This potentially allows the full cost of qualifying assets to be deducted in the first year. Property placed in service between January 1 and January 19, 2025, is limited to 40% bonus depreciation under the prior TCJA phase-down schedule. The 100% rate applies to 2026 and beyond, with no currently scheduled phase-down.
Bonus depreciation is generally taken automatically unless the taxpayer elects out. It may be combined with standard MACRS depreciation on the remaining basis of any asset not fully expensed.
Cost Segregation Studies
A cost segregation study is an engineering-based analysis that reclassifies components of a building into shorter MACRS recovery periods. Items like lighting fixtures, floor coverings, certain HVAC components, and site improvements may qualify for 5-year, 7-year, or 15-year depreciation instead of the standard 27.5 or 39 years. With 100% bonus depreciation now available, these reclassified assets may potentially be fully deducted in the year the property is placed in service.
Cost segregation studies typically range from $5,000 to $50,000 depending on the property's size and complexity, but they may generate significant front-loaded tax savings. Under IRC Section 481(a), taxpayers may be able to apply cost segregation retroactively through a catch-up deduction, which means investors who did not perform a study when they acquired the property may still benefit.
For a deeper look at how cost segregation works, see our cost segregation study guide. Investors in convenience store or retail properties may also find our C-store bonus depreciation guide useful.
The strategies discussed below involve complex tax provisions. This content is for educational purposes only and does not constitute tax advice. Consult your CPA or tax attorney before implementing any tax strategy.
Strategies to Reduce or Defer Capital Gains Tax
Federal tax law provides several mechanisms that may allow investors to defer, reduce, or potentially eliminate capital gains tax on real estate sales. Each mechanism has its own rules, timelines, and trade-offs.
1031 Exchange (Like-Kind Exchange)
A 1031 exchange under IRC Section 1031 may allow an investor to defer all capital gains tax (including depreciation recapture) by reinvesting the net proceeds from a property sale into replacement real property of equal or greater value. Both the relinquished property (the one being sold) and the replacement property are generally required to be held for investment or productive use in a trade or business. Personal residences and properties held primarily for resale (dealer property) generally do not qualify.
The exchange generally must follow strict timelines. The investor typically has 45 days from the closing of the relinquished property to identify potential replacement properties in writing, and 180 days to close on the replacement. A qualified intermediary (QI) is generally required to hold the sale proceeds during the exchange period; if the investor takes possession of the funds at any point, the exchange may fail and the full gain may become taxable.
Investors may identify up to three replacement properties regardless of value, or more properties provided their combined value does not exceed 200% of the relinquished property's sale price. Delaware Statutory Trusts (DSTs), which hold fractional interests in institutional-grade real estate, may qualify as replacement property under IRS Revenue Ruling 2004-86. DSTs can be a practical option for investors who seek to defer capital gains while transitioning out of active property management.
For a deeper explanation of 1031 exchange mechanics, see our complete 1031 exchange guide. Our article on the 1031 exchange capital gains loophole covers common planning strategies.
Primary Residence Exclusion (Section 121)
IRC Section 121 may allow homeowners to exclude up to $250,000 of capital gains ($500,000 for married couples filing jointly) from the sale of a primary residence. To potentially qualify, the seller is generally required to have owned the property and used it as a principal residence for at least two of the five years preceding the sale. The two years do not need to be consecutive.
Some investors attempt to use this exclusion by converting a rental property to a primary residence. While this is permitted, the rules are restrictive. Under IRC Section 121(b)(4), enacted in 2008, any period of nonqualifying use (time the property was used as a rental rather than a primary residence) after January 1, 2009, may reduce the excludable gain proportionally. Depreciation recapture from the rental period is generally understood to remain fully taxable regardless of the conversion. Additionally, properties acquired through a 1031 exchange are generally required to be held for at least five years before the Section 121 exclusion may become available.
Opportunity Zone Investments
Qualified Opportunity Zones, established under IRC Section 1400Z, may allow investors to defer capital gains by reinvesting them into Qualified Opportunity Funds (QOFs) within 180 days of realizing the gain. The program was made permanent by the OBBBA in 2025.
For investments made before December 31, 2026, the original gain is deferred until the earlier of December 31, 2026, or the date the QOF investment is sold. The primary long-term benefit is tax-free appreciation: if the QOF investment is held for at least 10 years, the investor's basis adjusts to fair market value at the time of sale, potentially eliminating capital gains tax on appreciation within the fund, provided all holding period and eligibility requirements are met. Investors should consult a qualified tax professional to evaluate eligibility.
For investments made after December 31, 2026, the program offers a five-year deferral of the original gain, a 10% basis step-up at the five-year mark, and the same tax-free appreciation benefit for 10-year holds.
Installment Sales
An installment sale under IRC Section 453 may allow a real estate seller to spread capital gain recognition over multiple tax years by receiving payments over time rather than in a lump sum. The taxable portion of each payment is determined by the gross profit ratio: total gain divided by total contract price. Only the principal portion of each payment is subject to tax; interest is taxed separately as ordinary income.
This approach may help investors stay in lower tax brackets by avoiding a large one-time gain. The installment method generally applies automatically to qualifying non-dealer real property sales unless the taxpayer elects out. Sellers report installment income annually on IRS Form 6252. For obligations exceeding $150,000 where the seller's total outstanding installment obligations exceed $5 million, interest charges may apply under IRC Section 453A.
Charitable Remainder Trusts
A charitable remainder trust (CRT) is an advanced strategy primarily suited to philanthropic investors with substantial unrealized gains. The investor transfers appreciated property to an irrevocable trust, which may sell the property without recognizing capital gain (the trust is generally tax-exempt under IRC Section 664(c)). The trust then reinvests the full proceeds and pays the donor an income stream, either as a fixed annuity (CRAT) or a percentage of trust assets revalued annually (CRUT), for life or a term of up to 20 years.
The donor may receive an immediate partial charitable deduction based on the present value of the remainder interest that will pass to a qualified charity. Income distributions are generally taxed to the donor under tiered rules in IRC Section 664(b). CRTs involve significant legal complexity and are typically appropriate only for investors with gains large enough to justify the setup and administration costs.
For additional strategies for managing capital gains on rental properties, see our guide on how to avoid capital gains tax on rental property.
Step-Up in Basis and Inherited Property
The step-up in basis is one of the most commonly discussed tax provisions in estate planning for real estate investors. Under IRC Section 1014, when property passes from a decedent to an heir, the heir's cost basis resets to the property's fair market value at the date of death (or an alternate valuation date under IRC Section 2032).
How the Step-Up Eliminates Unrealized Gains
This basis adjustment may effectively erase all unrealized capital gains accumulated during the decedent's lifetime. In a hypothetical example, consider a property purchased for $500,000 that appreciates to $2,000,000 by the time the owner dies. The heir's new cost basis would generally be $2,000,000. If the heir sells the property at that price, generally no capital gains tax would be owed. Generally, only appreciation occurring after the date of death is taxable to the heir. Actual tax outcomes depend on individual circumstances and should be reviewed with a qualified tax professional.
In community property states, both halves of a jointly owned property may receive a full step-up when one spouse dies, under IRC Section 1014(b)(6). This is generally understood as a meaningful advantage over common-law states, where typically only the deceased spouse's share receives the adjustment.
Estate Planning Implications
The step-up in basis creates an incentive for some investors to hold appreciated real estate through death rather than sell during their lifetime. This strategy may significantly reduce or potentially eliminate capital gains tax for heirs on appreciated real estate, though it generally should be weighed against liquidity needs, portfolio concentration risk, and the investor's overall estate plan.
The federal estate tax exemption for 2025 is $13.99 million per individual ($27.98 million for married couples). Beginning in 2026, the exemption increases to $15 million per individual ($30 million for married couples) under the OBBBA, which made the higher exemption permanent with no sunset provision. Estates below these thresholds generally owe no federal estate tax, and the step-up in basis generally applies regardless of whether the estate is subject to estate tax.
For a complete discussion of how inherited property is taxed and strategies for heirs, see our guide on how to avoid capital gains tax on inherited property.
Choosing the Right Strategy
No single tax strategy is optimal for every investor. The appropriate approach depends on the investor's goals, timeline, income level, and tolerance for complexity. The following table compares the major strategies discussed in this guide.
| Strategy | Best For | Tax Benefit | Complexity |
|---|---|---|---|
| 1031 Exchange | Active investors selling and reinvesting in real estate | Potential deferral of capital gains and depreciation recapture | Medium to high |
| Section 121 Exclusion | Homeowners selling a primary residence | Potential exclusion of up to $250,000 / $500,000 in gains | Low |
| Opportunity Zones | Investors with recently realized capital gains | Potential deferral plus potentially tax-free appreciation after 10 years | Medium |
| Installment Sale | Sellers who prefer income spread over multiple years | Potential deferral across tax years | Medium |
| Charitable Remainder Trust | Philanthropic investors with large unrealized gains | Potential deferral, income stream, and charitable deduction | High |
| Depreciation and Cost Segregation | Rental property owners seeking annual deductions | Potential reduction of taxable rental income | Medium to high |
| Step-Up in Basis | Estate planning and wealth transfer to heirs | Potential elimination of lifetime unrealized gains | Low |
| Real Estate Professional Status | Full-time real estate professionals with rental losses | Potential unlimited deduction of rental losses against active income | High |
| QBI Deduction | Rental operators with qualifying business income | Potential 20% deduction on qualified rental income | Medium |
Many of these strategies can be combined. For example, an investor might use depreciation and cost segregation to reduce taxable rental income during the holding period, execute a 1031 exchange at the time of sale to defer capital gains, and eventually benefit from a step-up in basis through estate planning. A qualified tax professional can help evaluate which combination makes sense for a particular situation.
Working With Tax Professionals
The tax code provisions relevant to real estate investors are numerous and interconnected. General-practice accountants are capable of handling standard tax filings, but they may not be familiar with strategies such as cost segregation studies, REPS elections, 1031 exchange structuring, or opportunity zone compliance. Investors with significant real estate holdings benefit from working with professionals who specialize in real estate taxation.
When selecting a tax advisor, relevant experience matters more than credentials alone. Investors may want to look for professionals who have handled 1031 exchanges, performed or coordinated cost segregation studies, advised clients on REPS qualification, and structured entity arrangements for real estate portfolios. CPAs, tax attorneys, and enrolled agents can all serve this role, depending on the complexity of the situation.
Timing is also important. Many of the strategies discussed in this guide require advance planning. A 1031 exchange is generally required to be structured before the sale closes. REPS qualification generally requires meeting hour thresholds throughout the tax year. Opportunity zone investments are generally required to be made within 180 days of realizing a capital gain. Engaging a tax professional before a transaction, rather than after, preserves the widest range of options.
This guide is intended for educational purposes only. It does not constitute tax, legal, or investment advice, and should not be relied upon as a substitute for consultation with a qualified professional. Tax laws and regulations are subject to change, and individual circumstances vary. Consult a qualified tax advisor before making any tax-related decisions regarding your real estate investments.
Anchor1031 specializes in the 1031 exchange component of a broader tax strategy — connecting investors with pre-vetted DSTs, TICs, and private placements through our marketplace. With $1.2B+ in cumulative real estate experience across 300+ 1031 transactions, our team can help with the exchange and replacement property side of an investor's plan. Schedule a consultation to get started.
In Summary
- * Capital gains tax rates may range from 0% to 23.8% federally, with state taxes potentially adding further liability
- * Depreciation generally provides annual “phantom” deductions; cost segregation may accelerate these into earlier years
- * 1031 exchanges may defer capital gains and depreciation recapture when reinvesting in like-kind property
- * Opportunity zones, installment sales, and charitable trusts may offer additional deferral and reduction paths
- * The step-up in basis may potentially eliminate a lifetime of unrealized gains for heirs
- * REPS and the QBI deduction may potentially reduce annual tax on rental income
- * Many strategies can be combined; consult a qualified tax professional to evaluate your situation
About the Author
Thomas Wall, Partner
Thomas Wall is a Partner at Anchor1031, where he specializes in educating clients about 1031 exchanges, private real estate offerings, and REITs. With nearly a decade of experience in alternative investments and real estate, Mr. Wall has helped investors through hundreds of 1031 exchanges, placing over $230M of equity into real estate.
Understanding Real Estate Taxes
Capital Gains & Tax Calculations
Depreciation Recapture Tax on Real Estate
How depreciation recapture works, the 25% federal rate, calculation methods, and strategies to defer or reduce recapture tax
How to Avoid Capital Gains Tax on Rental Property
Strategies for deferring or reducing capital gains taxes when selling rental properties
How to Avoid Capital Gains Tax on Inherited Property
Understanding step-up in basis and tax strategies for inherited real estate
1031 Exchange Calculator
Estimate your potential tax savings by comparing a taxable sale vs. a 1031 exchange
Tax Deferral & Depreciation Strategies
1031 Exchange Capital Gains Loophole
How 1031 exchanges enable indefinite tax deferral on real estate capital gains
How to Shelter Rental Income
Tax strategies for sheltering rental income through 1031 exchanges and depreciation
Cost Segregation Study Guide
How cost segregation studies accelerate depreciation deductions on commercial and residential rental properties
C-Store Bonus Depreciation Guide
Specialized guide to bonus depreciation tax benefits for convenience store and gas station investments
Opportunity Zone Investing
Opportunity Zone Investing Hub
Qualified Opportunity Funds offer a three-part tax incentive: capital gains deferral, gain reduction, and tax-free appreciation after 10 years. The program became permanent under the OBBBA with restructured benefits effective January 1, 2027. Explore our complete 7-article learning path.
Ready to Explore Tax-Deferred Investments?
Learn how 1031 exchanges and DST investments can help defer capital gains taxes. Browse our marketplace or learn about the 1031 exchange process.
Current Tax-Deferred Investment Opportunities
Explore our vetted DST investments for 1031 exchanges
Cunat Exchange X DST
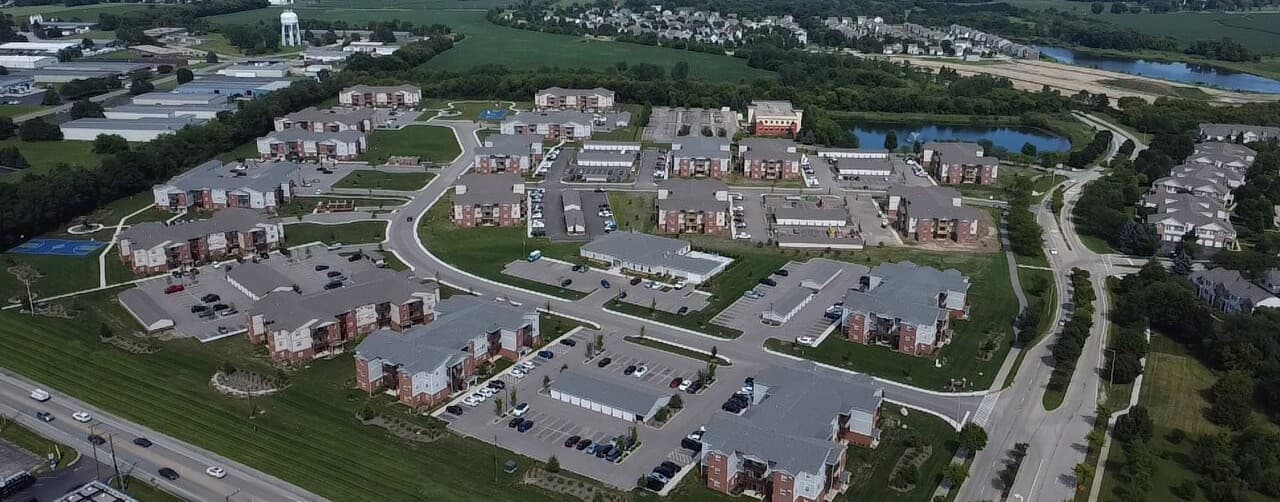
Cunat Exchange X DST is a new Delaware statutory trust formed on July 30, 2026 pursuant to a Trust Agreement dated as of July 30, 2026, which is attached hereto as Exhibit A. The Trust acquired the following 540-unit multifamily residential complex with approximately 236,412 rentable square feet on approximately 3.97 acres located at 1840 Aastri Drive, McHenry, Illinois 60050 and commonly known as The Residences of Fox Meadows. Cunat, Inc., an Illinois corporation is the Sponsor of this Offering and the present owner of the Trust. The Residences of Fox Meadows is a 540-unit multifamily property comprised of 18 three 3-story buildings with an aggregate of approximately 236,412 rentable square feet on approximately 3.97 acres located 1840 Aastri Drive, McHenry, Illinois 60050. The improvements are considered to be in good overall condition. The Property has 1,083 parking spaces. The Property was constructed in 2024 to 2025. The Property is a brand new construction apartment community located in the growing city of McHenry, Illinois. It offers spacious one-bedroom, one-bedroom with den, and multiple two-bedroom/two-bathroom floor plans. Each newly constructed residence features contemporary finishes and premium conveniences, including, but not limited to a fully equipped kitchen with stainless steel appliances, a full-size washer and dryer, individually controlled heating and air conditioning, and a private balcony or patio, as well as secure intercom-access buildings, garages, 24-hour maintenance. Resident amenities include, but are not limited to, a fitness center, indoor heated swimming pool, outdoor swimming pool, basketball courts, and playground areas. The community center also features a spacious party and meeting room. The Property is located near schools, shopping, restaurants, transportation, and recreational destinations. Pet-friendly accommodations are also available. The Trust purchased the Property with a new loan in the amount of $84,375,000 as set forth below obtained from JLL Real Estate Capital, LLC, a Delaware limited liability company, pursuant to Freddie Mac’s multifamily lending program, which Loan closed on the Loan Closing Date and is secured by the Property. The Loan has a term of 10 years and is interest only at a fixed rate equal to 5.43% per annum with interest only payments for the entire term of the Loan.
CS1031 Texas Active Living New Braunfels, DST
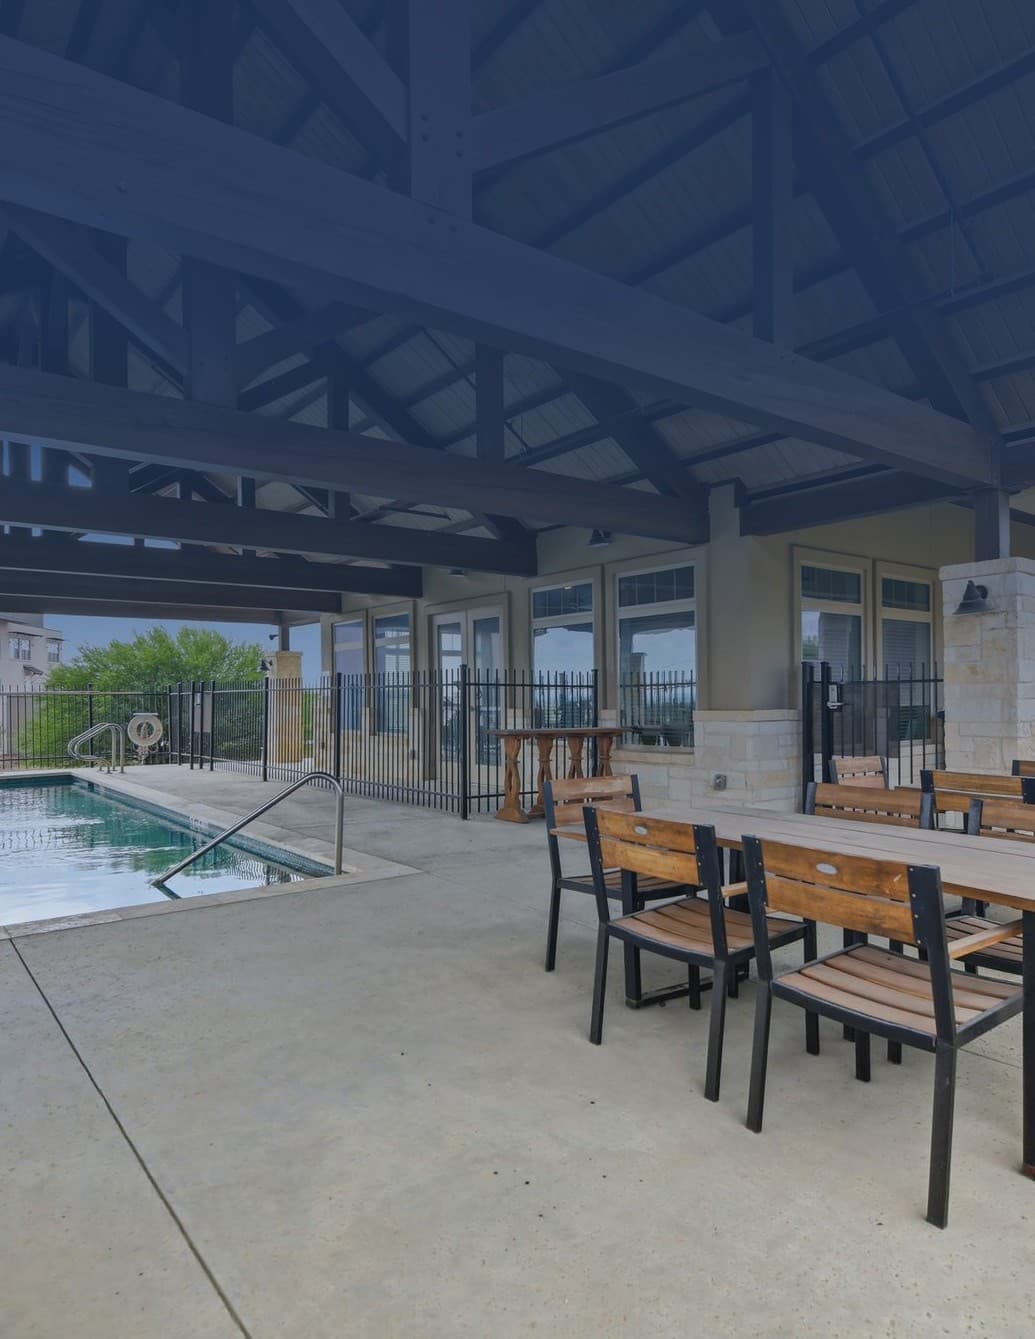
CS1031 Texas Active Living New Braunfels, DST, a Delaware statutory trust, has been formed for the purpose of acquiring Emerald Cottages of New Braunfels, a recently constructed, boutique active adult community with 72 single-family-style cottage homes, located at 3025 Oak Run Parkway, New Braunfels, Texas 78132. The Property was completed in 2024 and is comprised of 17 single-story residential buildings and one standalone clubhouse with an outdoor pool, situated on approximately 11 acres of land. The Property consists of 12 one-bedroom, one-bathroom units and 60 two-bedroom, two-bathroom units, with an average unit size of 1,275 square feet. The cottage homes at the Property were designed with the active adult demographic in mind. Open floor plans feature granite and stone countertops, wood and carpet flooring, a fully equipped kitchen with stainless steel appliances, dishwasher, disposal and microwave, an in-unit washer and dryer, central heating and cooling, and accessibility features throughout including zero-threshold showers. Each unit features a private entrance and an attached garage. Community amenities center on the clubhouse, which houses a fitness room, business center, and dining room, and extends to a swimming pool and a BBQ and picnic area. On-site management maintains a regular social calendar of exercise classes, community events, and entertainment for residents. New Braunfels is located in Comal County, strategically positioned between San Antonio and Austin. The city has an estimated population of approximately 122,000, while Comal County totals roughly 209,000 residents. New Braunfels sits about 34 miles northeast of San Antonio and 48 miles south of Austin, providing convenient access to both major employment centers while maintaining a distinct local identity. The county’s median household income is approximately $101,889, reflecting an affluent and growing suburban market. The Property is in the process of completing its initial lease-up. As of the date of this Memorandum, the Property was approximately 87.5% occupied and 91.7% leased.
Driftwood Hotel Income I, DST
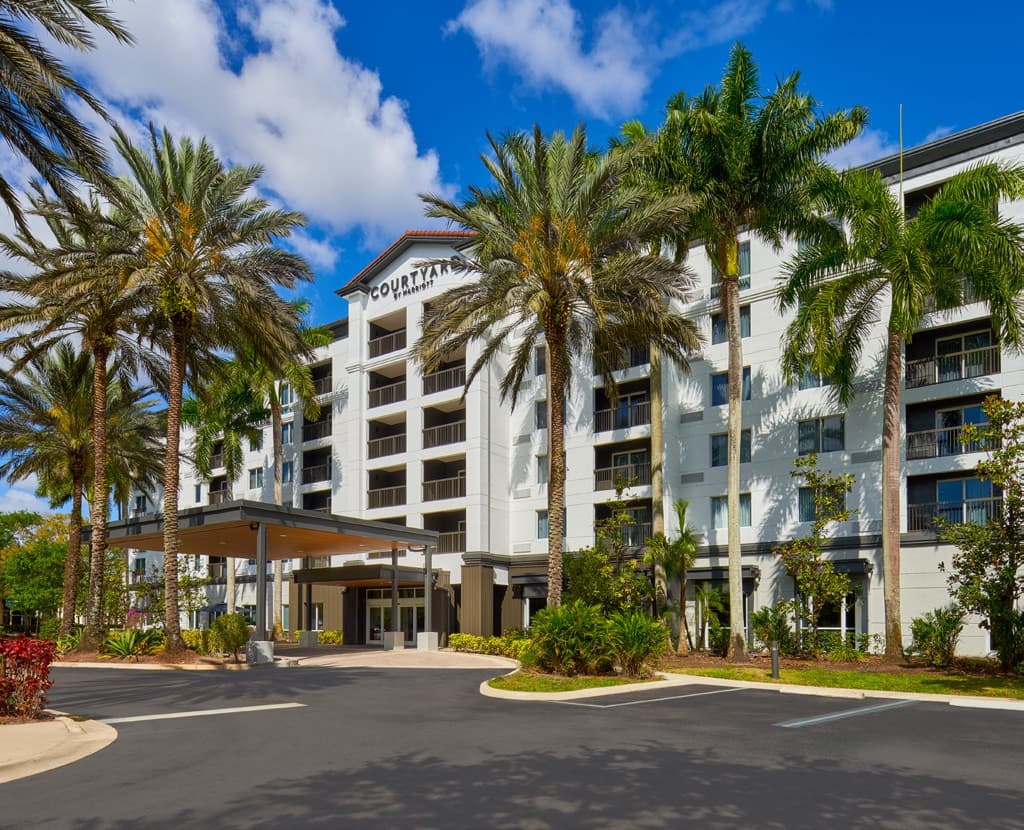
The Trust owns a fee simple interest in the land and improvements located at 2000 N. Commerce Parkway, Weston, FL 33326, which includes the Courtyard Fort Lauderdale Weston hotel property that is located in a sought-after suburban market of Florida. The Hotel is a recently renovated 176-key, six story building that also includes The Bistro, an on-site food and beverage outlet, and three functional meeting spaces. The Hotel benefits from a large corporate and medical office presence that drives year-round lodging demand. The Hotel completed approximately $5 million in guest-facing renovations to rooms and public spaces in 2024, which positions it well for new ownership to drive further income growth. Pursuant to the Franchise Agreement, the Hotel is operated under the name Courtyard by Marriott, which is a brand of Marriott International, Inc.
NexPoint Marina II DST
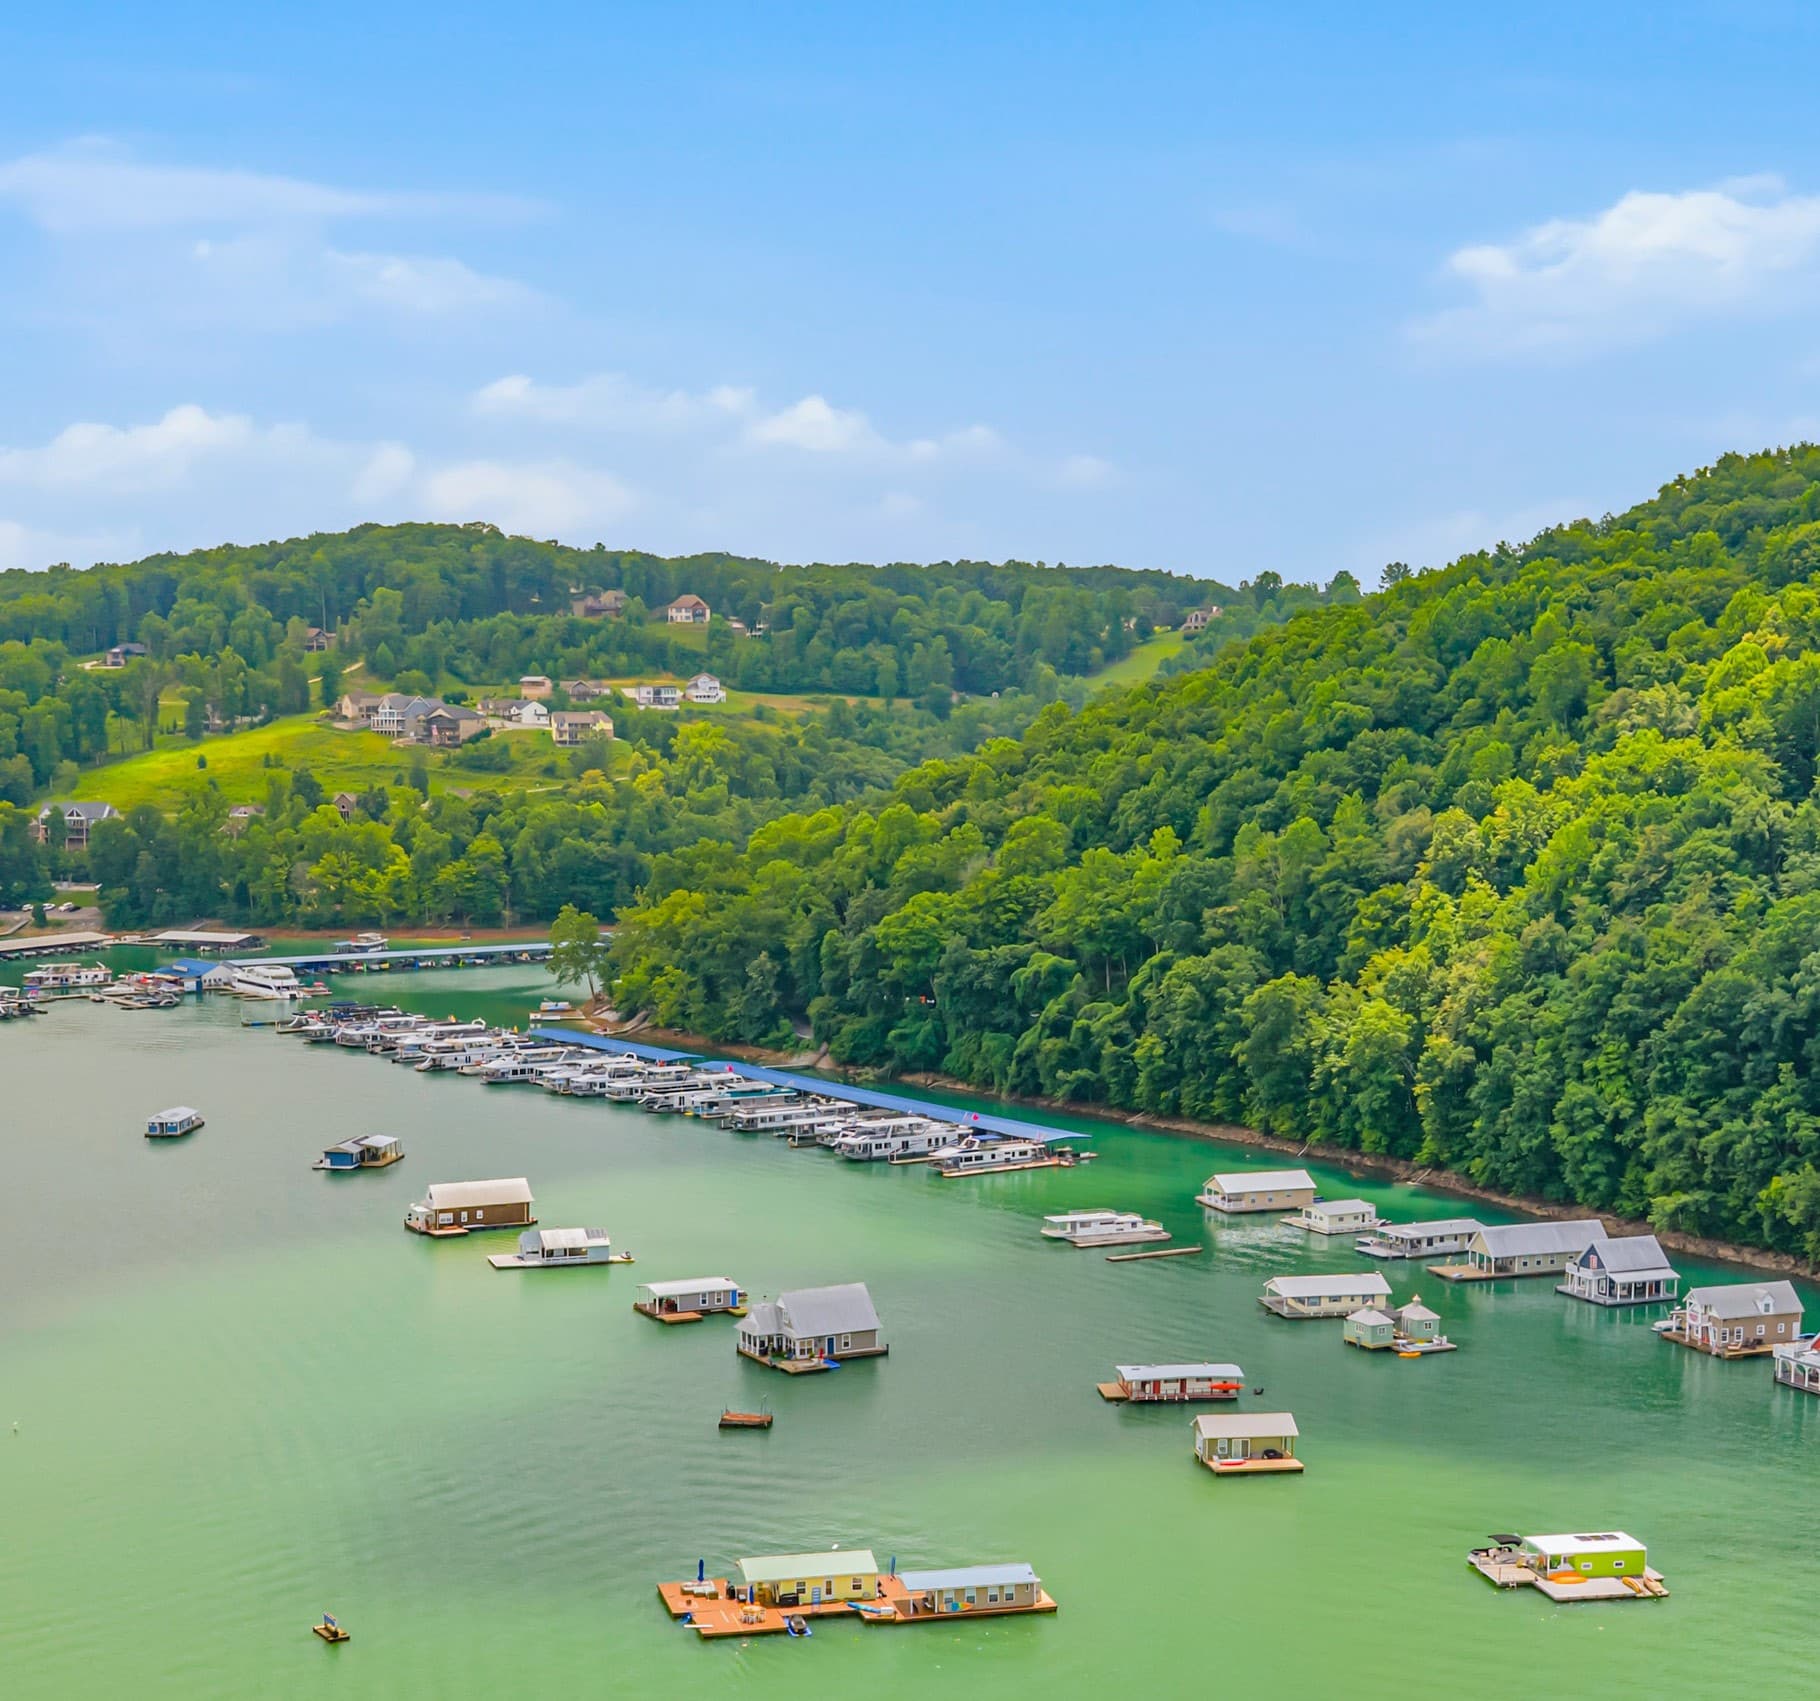
We are pleased to present the NexPoint Marina II DST, an offering comprised of two stabilized, full-service marina assets with demonstrated demand, high occupancy, and embedded growth potential. Located in Tennessee and Kentucky both properties are characterized by strong underlying demand and limited slip availability. The Stardust Property (located in Andersonville, TN) and the Kuttawa Property (located in Kuttawa, KY) each serve as a regional destination marinas. Given their close proximity to Knoxville and Nashville, respectively, they both draw local and visiting boaters to their waterfront sites. They benefit from established operating histories, strategic locations within highly trafficked recreational boating corridors, the durable fundamentals of the U.S. recreational boating market, and diversified revenue streams that include fuel, food & beverage, retail, and rental offerings which enhance the Master Tenants' ability to meet their Master Lease obligations. Importantly, we believe both assets offer embedded growth potential through recently completed and planned slip expansions, positioning the portfolio to capture waitlist demand and drive incremental revenue. The Sponsor believes that the Properties present an attractive long-term investment opportunity due to, in part, favorable submarket demographics, nearby retail drivers, continued and strengthening demand for Marina Properties, constrained supply of Marina Properties, the high quality of each asset, swift physical occupancy lease-up velocities, and the long-term strength of the sector.
Disclosure
Tax Complexity and Investment Risk
Tax laws and regulations, including but not limited to Internal Revenue Code Section 1031, bonus depreciation rules, cost segregation studies, and other tax strategies, contain complex concepts that may vary depending on individual circumstances. Tax consequences related to real estate investments, depreciation benefits, and other tax strategies discussed herein may vary significantly based on each investor's specific situation and current tax legislation. Anchor1031, LLC and Quincy Wells Capital, LLC make no representation or warranty of any kind with respect to the tax consequences of your investment or that the IRS will not challenge any such treatment. You should consult with and rely on your own tax advisor about all tax aspects with respect to your particular circumstances. Please note that Anchor1031 and Quincy Wells Capital, LLC do not provide tax advice.

The information contained in this article is for general educational purposes only and does not constitute legal, tax, investment, or financial advice. This content is not a recommendation or offer to buy or sell securities. The content is provided as general information and should not be relied upon as a substitute for professional consultation with qualified legal, tax, or financial advisors.
Tax laws, regulations, and IRS guidance regarding 1031 exchanges, opportunity zone investments, and related real estate strategies are complex and subject to change. Information herein may include forward-looking statements, hypothetical information, calculations, or financial estimates that are inherently uncertain. Past performance is never indicative of future performance. The information presented may not reflect the most current legal developments, regulatory changes, or interpretations. Individual circumstances vary significantly, and strategies that may be appropriate for one investor may not be suitable for another.
All real estate investments, including 1031 exchanges and opportunity zone investments, are speculative and involve substantial risk. There can be no assurance that any investor will not suffer significant losses, and a loss of part or all of the principal value may occur. Before making any investment decisions or implementing any 1031 exchange strategies, readers should consult with their own qualified legal, tax, and financial professionals who can provide advice tailored to their specific circumstances. Prospective investors should not proceed unless they can readily bear the consequences of potential losses.
While the author is a partner at Anchor1031, the views expressed are educational in nature and do not guarantee any particular outcome or create any obligations on behalf of the firm or author. Neither Anchor1031 nor the author assumes any liability for actions taken based on the information provided herein.